
Managing taxes is an important part of personal financial planning, especially for salaried employees, business owners, freelancers, and investors. In India, taxpayers may need to report their income, claim eligible deductions, calculate their tax liability, and comply with applicable filing requirements. Understanding these responsibilities can help individuals avoid unnecessary mistakes and maintain better control over their finances. Although tax filing may initially appear complicated, knowing the basic rules makes the process considerably easier.
An income tax return is a formal statement of income earned during a financial year, along with relevant deductions, exemptions, taxes paid, and other required financial details. It allows the Income Tax Department to assess whether a taxpayer has paid the correct amount of tax. Depending on individual circumstances, filing may be mandatory or voluntary. Even when a person is not required to pay tax, submitting a return can sometimes be useful for financial documentation, loan applications, and claiming eligible refunds.
Tax rules, filing procedures, and available benefits can change from year to year. Therefore, taxpayers should understand the financial year and assessment year applicable to their situation instead of relying on outdated information. A careful approach helps people make informed decisions, maintain accurate records, and complete their tax responsibilities with greater confidence.
What Is an Income Tax Return?
An income tax return is a declaration submitted to the tax authorities that explains how much income a person or entity earned during a particular financial year. It can include salary, income from a business or profession, rental earnings, interest from savings and deposits, capital gains, and other taxable receipts. The return also records eligible deductions, exemptions, tax credits, and taxes already paid through methods such as Tax Deducted at Source (TDS) or advance tax.
The primary purpose of filing is to calculate the final tax position of the taxpayer. If the tax already paid exceeds the amount due, the taxpayer may qualify for a refund after the return is processed and the claim is verified. If the tax paid is insufficient, additional tax may be payable, subject to the applicable rules. Filing also creates an official record of reported income, which can be helpful when demonstrating financial stability for certain banking, visa, or lending requirements. However, acceptance of a return does not automatically mean that every reported claim has been independently approved.
Who Should File an Income Tax Return in India?
The requirement to file depends on several factors, including total income, the applicable tax regime, the taxpayer’s category, and specific conditions prescribed under the Income-tax Act. Individuals whose income exceeds the applicable basic exemption limit generally need to examine their filing obligations. Certain taxpayers may also be required to file even when their income falls below that limit, depending on specific financial transactions, asset-related conditions, or other statutory requirements.
Salaried employees are often familiar with TDS because employers deduct tax from their monthly salaries. However, TDS does not always settle the complete tax liability. A person may have additional income from fixed deposits, rental properties, freelance projects, or investments that affects the final calculation. Similarly, business owners and self-employed professionals must evaluate their income and applicable reporting requirements carefully. Some individuals may choose to file voluntarily to claim an eligible refund or establish a documented income history. The correct approach is to assess the applicable rules rather than assuming that low income or employer deductions automatically remove the need to file.
Understanding the Financial Year and Assessment Year
One common source of confusion is the difference between the financial year and the assessment year. The financial year is the period in which income is earned, while the assessment year is the following year in which that income is assessed and reported through the relevant tax return. Understanding this distinction is essential when selecting the correct filing period or interpreting a tax notification.
For example, income earned between 1 April 2025 and 31 March 2026 belongs to Financial Year 2025–26 and is generally reported in Assessment Year 2026–27. A taxpayer filing during the assessment year must use the forms and rules applicable to that period. Selecting an incorrect year can create reporting errors or require additional corrective action. Before beginning the filing process, individuals should confirm their financial year, assessment year, and the current filing instructions applicable to their taxpayer category.
Old Tax Regime vs New Tax Regime
India provides different tax-regime options for eligible taxpayers. The new tax regime generally offers revised slab rates and a more limited set of deductions and exemptions, while the old tax regime allows specified deductions and exemptions subject to their individual conditions. The most suitable option depends on the taxpayer’s income, eligible investments, housing arrangements, insurance payments, and other relevant financial circumstances.

Under the old regime, eligible taxpayers may be able to claim certain deductions for qualifying investments, health insurance premiums, and other permitted expenses. The new regime generally offers a different structure, with several deductions and exemptions unavailable or restricted, although certain benefits remain available under specific provisions. The new regime is generally the default regime for individuals, subject to applicable rules and exceptions. Taxpayers with business or professional income may face additional conditions when choosing or changing regimes. Therefore, comparing the actual tax payable under both options is more reliable than choosing solely on the basis of a lower-looking tax rate.
Documents Required for Filing
Preparing the necessary documents before starting the filing process can save time and reduce the possibility of mistakes. The documents required depend on whether the taxpayer earns a salary, operates a business, receives rental income, or earns money through investments. Salaried employees commonly need Form 16, salary statements, and details of tax deductions. Bank interest certificates, investment records, housing-loan documents, and information about other income may also be relevant when calculating the final tax liability.
Taxpayers should not rely exclusively on the information provided by their employers. They should review their Annual Information Statement (AIS), Taxpayer Information Summary (TIS), and Form 26AS, as applicable, to compare available financial information and tax-payment records. Differences between these records and personal documents should be investigated before submission.
The following records are commonly useful during preparation:
-
PAN, Aadhaar details where applicable, and an active bank account.
-
Form 16, salary slips, and records of other income.
-
Bank interest statements and investment or capital-gains statements.
-
Supporting documents for eligible deductions, exemptions, and tax payments.
Not every taxpayer needs every document listed above. For example, a freelancer may need invoices, business expense records, and details of advance tax payments, whereas a salaried employee with no additional income may have a simpler set of records. Maintaining digital copies throughout the year makes it easier to verify figures and respond to questions if clarification is needed later.
How to File an Income Tax Return Online
Online filing has made tax compliance more accessible to individuals across India. The process generally involves signing in to the official income tax e-filing system, selecting the appropriate assessment year, choosing the correct return form, entering income details, reviewing tax calculations, and submitting the completed return. The exact steps can vary according to the taxpayer’s income sources, residential status, business activities, and other circumstances.
Before selecting a form, taxpayers should confirm that it matches their income profile. A return intended for certain salaried individuals may not be suitable for someone with business income or complex capital gains. After entering the required details, the taxpayer should compare the figures with available tax statements and supporting documents. Any tax payable should be settled according to the applicable instructions before completing the submission.
After submission, verification is an essential step. An income tax return generally needs to be verified through an available electronic method or another permitted procedure within the prescribed period. Merely submitting the form without completing the required verification can leave the filing process incomplete. Once verification is completed, taxpayers should save the acknowledgement and monitor the processing status. If a refund is due, they should also ensure that their bank account details are correct and that the account meets the relevant validation requirements.
Common Income Tax Return Forms and Their Uses
Different forms are designed for different categories of taxpayers. Selecting the correct form is important because each form has eligibility conditions relating to income sources, residential status, and other factors. The following table provides a general overview of commonly used individual return forms in India.
| Return form | General purpose |
|---|---|
| ITR-1 | Eligible resident individuals with relatively straightforward income, subject to prescribed conditions |
| ITR-2 | Individuals and Hindu Undivided Families not eligible for ITR-1 and without income from business or profession |
| ITR-3 | Individuals and Hindu Undivided Families with income from business or profession |
| ITR-4 | Eligible individuals, Hindu Undivided Families, and firms other than LLPs using specified presumptive taxation provisions |
These descriptions are general rather than exhaustive. Each form has specific eligibility conditions, restrictions, and reporting requirements that may change. For instance, the existence of certain income types or particular financial circumstances can make a simpler form unsuitable. Taxpayers should consult the instructions for the relevant assessment year before making their selection, particularly when they receive income from several sources or operate a business.
Important Deadlines and Consequences of Late Filing
Filing deadlines are important because missing the applicable date may lead to additional costs or limit certain options. The due date depends on the taxpayer’s category and whether the return is subject to special reporting requirements, such as an audit. Deadlines can also be extended through official notifications. For this reason, taxpayers should check the current assessment-year instructions rather than assuming that the same date applies to everyone.
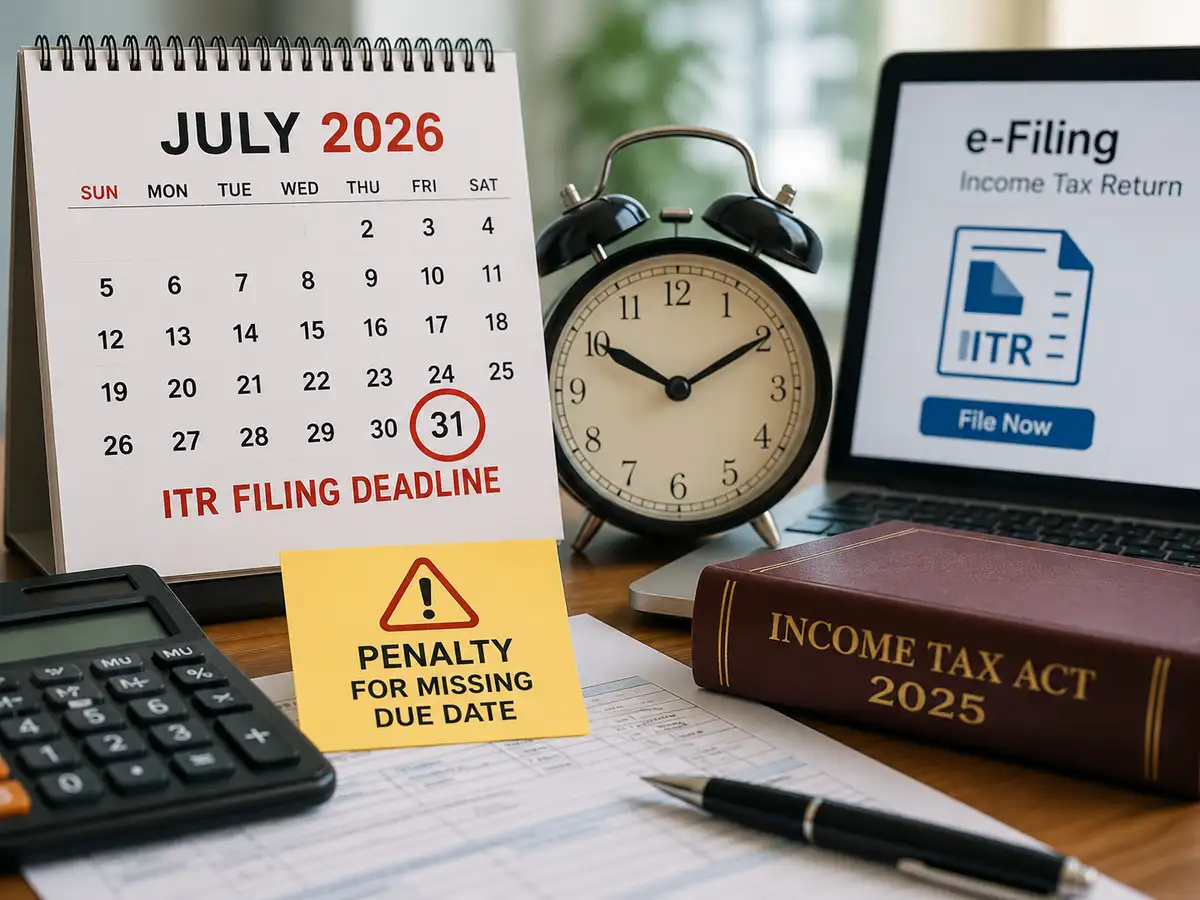
Late filing can result in a late-filing fee where applicable, interest on unpaid tax, and restrictions on certain loss carry-forward claims. It may also complicate refund processing or the correction of financial information. Depending on the circumstances, a belated return or another permitted filing mechanism may be available, but these options are subject to statutory time limits and conditions. Filing early gives taxpayers more time to resolve discrepancies, obtain missing documents, and correct mistakes before the deadline.
Common Mistakes to Avoid During Tax Filing
Many filing problems arise from small oversights rather than complicated tax calculations. Taxpayers may forget to report savings-account interest, overlook capital gains, enter incorrect deduction amounts, or select a form that does not match their circumstances. Some people assume that employer-provided Form 16 contains every detail needed for filing, even when they have additional income from other sources. Others submit the return but forget to complete verification, leaving an important requirement unfinished.
Another frequent mistake is claiming deductions without confirming eligibility. An investment or expense does not automatically qualify for a tax benefit simply because money was spent during the year. Each deduction has its own conditions, limits, and documentation requirements. Taxpayers should also verify bank account details, review personal information, and reconcile tax credits before submitting the form. A careful final review is usually more effective than rushing through the process at the last minute.
Benefits of Filing on Time
Filing a return within the applicable deadline can provide several practical benefits beyond meeting legal obligations. It creates a formal record of reported income, helps taxpayers claim eligible refunds, and makes it easier to maintain organized financial records. Individuals applying for loans may find previous returns useful when lenders assess income and repayment capacity, although lenders consider other documents and eligibility criteria as well. Similarly, individuals planning major purchases or financial commitments can use their tax records to review their earnings and financial position.
Timely filing also gives taxpayers an opportunity to identify discrepancies while supporting documents are readily available. If tax has been deducted in excess of the final liability, filing may help initiate the process of claiming an eligible refund. However, refunds are subject to applicable conditions, verification, and processing by the tax authorities. Filing alone does not guarantee a refund, and any outstanding tax liability must be addressed separately.
What to Do After Submitting Your Return
Completing the submission is not necessarily the final step. Taxpayers should ensure that verification has been completed, retain the acknowledgement, and check the processing status periodically. If the department issues an intimation or requests additional information, the taxpayer should read the communication carefully and respond within the prescribed timeframe. Any apparent discrepancy should be investigated using the original records rather than ignored.
If a mistake is discovered after submission, the available correction process will depend on the type of error, the assessment year, and the applicable statutory deadlines. A revised return may be permitted in some situations, while other cases may require a different procedure. Taxpayers should avoid submitting multiple returns without understanding the applicable rules. For complicated matters involving business income, substantial capital gains, foreign income, or disputed tax treatment, consulting a qualified tax professional can help prevent avoidable compliance problems.
Conclusion
Understanding the income tax return process is an important step toward responsible financial management. From identifying filing obligations and selecting the appropriate tax regime to gathering documents and completing verification, each stage contributes to accurate reporting. Taxpayers who maintain organized records throughout the year can reduce last-minute stress and make better-informed decisions about their financial responsibilities. The most effective approach is to review income from every relevant source, compare tax information with official records, confirm eligibility for deductions, and follow the instructions applicable to the correct assessment year. It is equally important to monitor deadlines and retain submission documents for future reference. Because tax provisions and filing requirements can change, checking current official guidance is preferable to relying on assumptions or outdated advice.